|
|
|
|
BK Opportunities
Fund 9
Quarterly Report | 30th September 2026
|
|
The final NAV and distribution of the BK Opportunities Fund 9 as of 30 September 2026 are:
|
| Distributing Class |
|
Accumulating Class |
NAV 103.99%
Distribution 1.5%
|
|
NAV 105.49%
|
Payments for the distribution classes will be around October 20th, 2026.
|
|
|
|
BK Opportunities Fund 9 final net performances
as of 30th September 2026
|
| Monthly Return (non-annualized) |
0.5% |
| Year-to-Date (non-annualized) |
4.2% |
| Annual Return since inception2 |
+13.6% |
| Cumulative Distributions since inception/October 20251 |
+1.5% |
| Cumulative Return since inception/October 20251 |
+5.5% |
|
|
1 — Weighted average distribution of all classes.
|
|
2 — Based on the weighted average internal rate of return (“IRR”) of all classes from their respective closing date at their respective entry price.
|
|
Market Commentary & Portfolio Overview
|
|
|
|
|
Q3 2026 ended the transatlantic split of Q2: both central banks are now hiking. Inflation reaccelerated on both sides as energy prices climbed, and the Fed joined the ECB with its first hike in three years. Growth held up better than feared, corporate earnings hit multi-year records, and leveraged finance finally saw M&A return in September. CLO markets kept running at a high pace as funding costs eased.
|
|
|
|
|
|
The Economy: Twin Hikes
|
|
The US economy grew at a 2.2% annualised rate in Q2, while euro area GDP rose 0.4%, double expectations, and the eurozone PMI reached a three-and-a-half-year high in September. Inflation is the common problem: US CPI rose to 3.7% in September, with a 9.1% jump in gasoline accounting for more than half the monthly increase, while euro area prices rose 3.8%. The ECB raised its deposit rate to 2.50% on 10 September, and on 16 September the Fed hiked by 25 bps, unanimously, for the first time in three years. Markets now price around 28 bps of further US hikes this year.
|
|
|
|
|
|
Corporate Markets: Earnings Boom
|
|
Profits surged on both sides. S&P 500 Q2 earnings grew 52.0%, driven by Big Tech, but the other 493 companies still grew 31.8%. In Europe, earnings rose 24.1%, the strongest since Q3 2022, mainly from energy, though growth ex-energy remained 11.5%–12%. The gap remains: US growth is tech-led, Europe’s is energy-led.
|
|
|
|
Corporate Credit: Credit Under Pressure
|
|
Lending conditions are tightening. Euro area banks tightened standards again in Q2 and expect further tightening in Q3. In the US, the syndicated market is winning back business from private credit: around $12bn of direct-lending deals were refinanced in the BSL market in Q3, the most since tracking began in 2022. Defaults remain low, but nearly a third of surveyed participants expect US loan default rates to reach or exceed 1.50%, from 0.87% today.
|
|
|
|
Loan Market: M&A Awakens
|
|
September marked a turning point. After a slow start to Q3, US M&A-related loan issuance reached $39.9bn for the quarter, with September alone at $30.6bn, the highest since January 2022. Software fell to just 10% of new issuance. In Europe, a busy September pipeline raised expectations of record monthly volume, after loan spreads hit nine-year tights in June. Pricing is diverging: US B-plus deals carried an average spread of S+289 this quarter, about 20 bps wider than at end-2025.
|
|
|
|
CLO Market: Lower Funding Costs
|
|
US CLO issuance stayed high but cooled through the quarter, from $46.4bn in July to $41.1bn in September, the lowest since April. New-issue AAA tranches priced at an average of 122 bps, and tighter AAA spreads pulled managers toward refinancings over resets. Year-to-date issuance reached $361.1bn in the US and €94.9bn in Europe. The arbitrage remains the constraint: US issuance runs about 20% below last year, mainly due to weak collateral formation and harder BSL arbitrage. Middle-market CLOs had their best month of 2026 in September at $6.8bn.
|
|
|
|
|
|
|
BK Opp. Fund 9: Performances
|
BK Opportunities Fund 9 (BK-9) was launched in October 2025. It has been actively
trading BBB, BB and B-rated tranches of US and European CLOs. Our portfolio is well
diversified across all sectors, with a very low idiosyncratic exposure. In addition to
capturing the usual extra return of CLOs from its niche market, we have employed various
structural arbitrage strategies, in some cases linked to the duration of our positions.
|
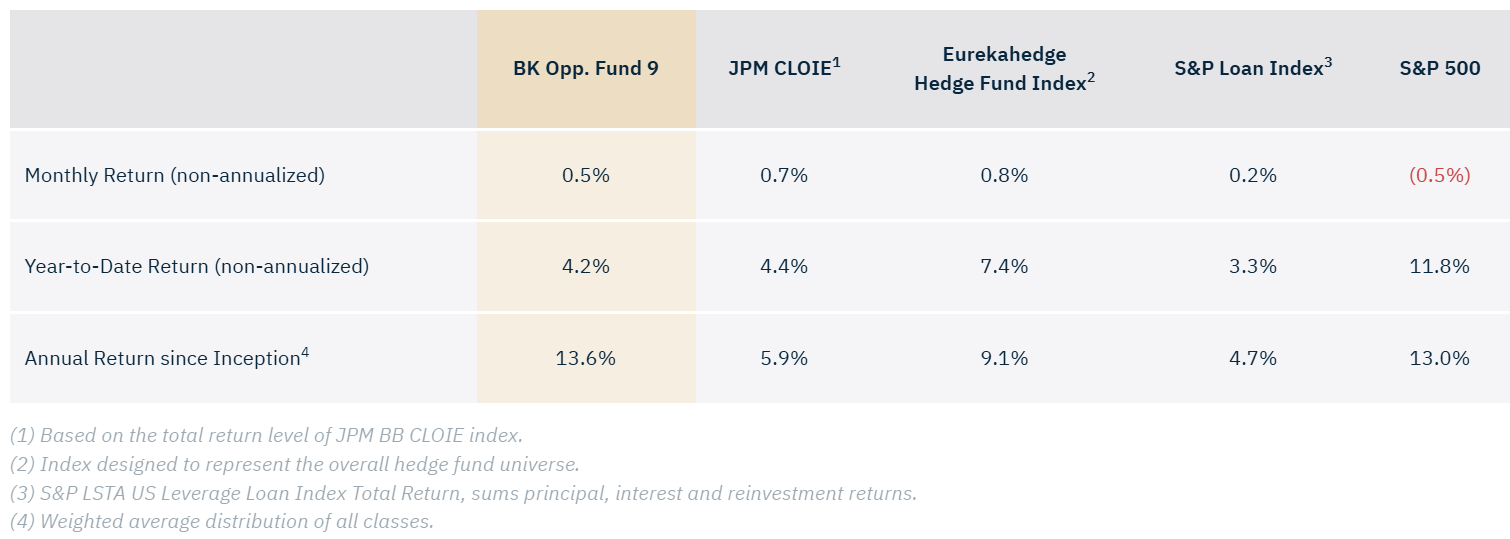
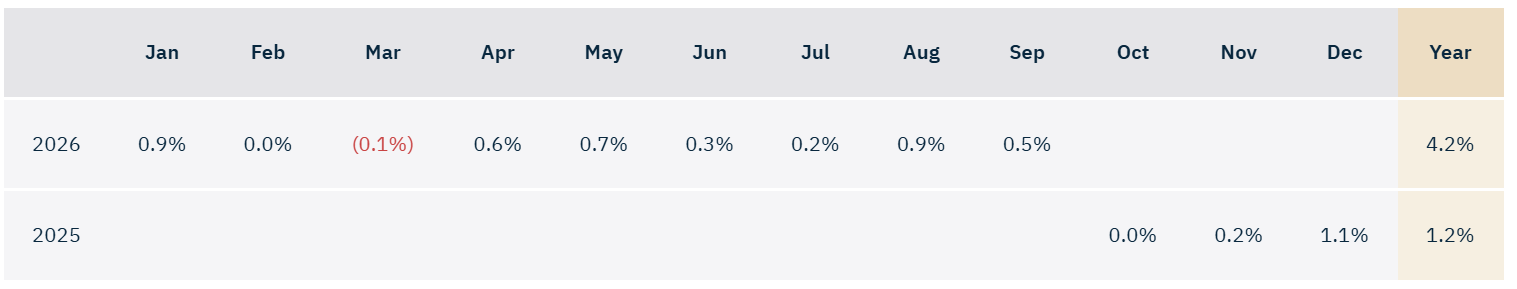
BK Opportunities Fund-9's monthly return is 0.5%, and its year-to-date return is 4.2%.
Based on the weighted-average return for each investor, the fund's annual return is
+13.6%, exceeding our expectations given the fund’s short life so far.
|
We are pleased to announce that BK-9 has declared its inaugural dividend distribution of
1.50% for holders of the Distributive classes, payable on October 20, 2026.
|
We continue to very actively manage the portfolio and anticipate returns to strengthen.
|
|
|
|
|
|
|
Fund and Market Performances as of 30th September 2026
|
|
|
|
|
Monthly Performances
|
|
|
|
|
|
|
Top 10 Industry Exposure
| Industry |
% of Portfolio |
| Healthcare & Pharmaceuticals |
11.1% |
| Services: Business |
9.9% |
| High-Tech Industries |
9.2% |
| Banking, Finance, Insurance & Real Estate |
8.4% |
| Hotel & Leisure |
5.0% |
| Chemicals, Plastics & Rubber |
4.8% |
| Construction & Building |
4.4% |
| Beverage, Food & Tobacco |
4.3% |
| Telecommunications |
4.2% |
| Capital Equipment |
3.4% |
|
Top 10 Issuers Exposure
| Issuer |
% of Portfolio |
| Liberty Global |
1.3% |
| Ineos Ltd |
1.2% |
| Vmed O2 UK |
0.9% |
| 3I Group |
0.6% |
| Kantar Global |
0.6% |
| Froneri Lux |
0.5% |
| Quimper Ab |
0.5% |
| Ion Platform |
0.5% |
| Boxer Parent Company |
0.5% |
| Skydance Corp |
0.5% |
|
|
|
|
|
|
Fund’s Summary
|
| Currency |
USD & EUR |
| Fund’s Inception |
October 2025 |
| Distribution |
Quarterly |
| Investment Manager |
Oristan Ireland DAC |
| Administrator |
Cafico International |
| Custodian |
CIBC Bank & Trust |
| Counsel |
Elvinger Hoss |
| Auditor |
Deloitte |
| Bloomberg Page USD Distributive |
LU3185323030 |
| Bloomberg Page USD Cumulative |
LU3185323204 |
| Bloomberg Page EUR Distributive |
LU3185323626 |
| Bloomberg Page EUR Cumulative |
LU3185327452 |
|
|
Portfolio Manager
Olivier Gozlan
|
|
|
|
|
|
|
|
|
|
This is not for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to law or regulation. The information contained herein is for information only and does not constitute an offer regarding any product. The document has been prepared by Oristan Ireland DAC and the data have not been audited nor verified. Past performance cannot indicate future performance. There is no assurance that the investment objective will be achieved and investment results may vary.
|
|
|
|
|
|
|
|
|