|
|
|
|
BK Opportunities
Fund 7
Quarterly Report | 30th Septembre 2026
|
|
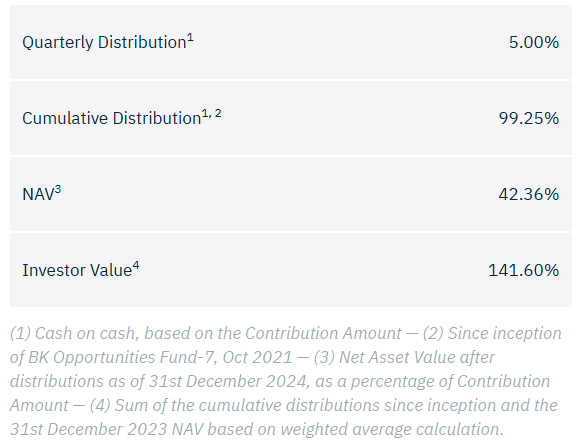
The final N.A.V. and distribution of BK Opportunities Fund-7 (Euro) as of September 30, 2026, are:
|
NAV
|
42.36%
|
Current Distribution
|
5.0%
|
Distributions Since Inception1
|
|
|
|
Payments will be made on or around October 30th, 2026.
|
|
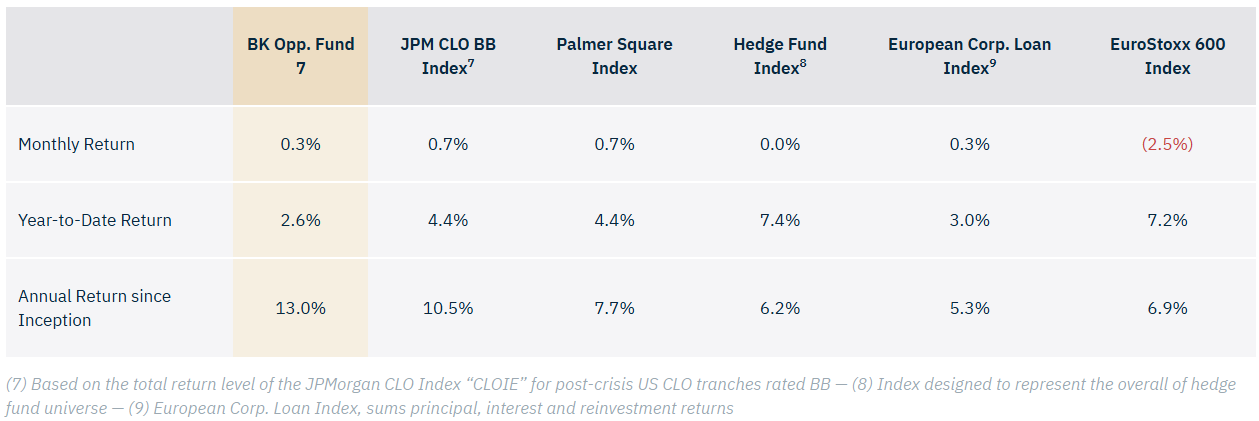
BK Opportunities Fund-7 final net performances
as of 30th September 2026
|
| Monthly Return (non-annualized) |
0.3% |
| Year-to-Date (non-annualized) |
2.6% |
| Annual Return since inception2 |
+13.0% |
| Cumulative Distributions since inception/October 20211 |
+103.9% |
| Cumulative Return since inception/October 20211 |
+49.0% |
|
|
1 — Weighted average distribution of all classes.
|
|
2 — Based on the weighted average internal rate of return (“IRR”) of all classes from their respective closing date at their respective entry price.
|
|
Market Commentary & Portfolio Overview
|
|
|
|
|
The euro area turned out more resilient than feared over the summer, but inflation came back harder. Growth beat forecasts and business surveys hit multi-year highs, while energy pushed inflation to 3.8% and the ECB delivered a second hike in September. Corporate profits jumped, though largely thanks to energy. Banks kept tightening, and CLO and loan markets stayed busy.
|
|
|
|
|
|
The Economy: Surprising Resilience
|
|
The eurozone economy expanded faster than expected in Q2: GDP rose 0.4% quarter-on-quarter, double the 0.2% expected, after being flat in Q1. Eurostat later put Q2 growth at 0.6%. Momentum held into Q3: the composite PMI rose to 53.1 in September from 52 in August, its highest level in nearly three and a half years, and all five countries covered by the survey grew for the first time since November. The downside is inflation. Prices rose 3.8% year-on-year in September, up from 3.2% in August, with energy prices up 18.8%. The ECB raised all three key rates by 25 bps, taking the deposit rate to 2.50%, as Middle East-related pressures are expected to keep inflation well above target for an extended period. It now projects inflation at 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028.
|
|
|
|
|
|
Corporate Markets: Energy-Fuelled Profits
|
|
Q2 earnings rose 24.1% year-on-year, the strongest quarterly growth since Q3 2022. Energy drove most of this, with EPS up 124% on sales up 36%, but the improvement was broader than in Q1: even excluding energy, growth was a robust 11.5%–12%. Sales grew 7.8%, the first clearly positive reading after four negative quarters. Dispersion remains sharp: consumer discretionary saw a 24% earnings decline. Deutsche Bank raised its full-year 2026 EPS growth forecast to 15% from 12%.
|
|
|
|
European Corporate Credit: Still Tightening
|
|
Banks tightened lending standards again in Q2, with a net 7% reporting stricter standards for loans to firms, while business borrowing picked up slightly. They remain highly attentive to geopolitical and energy risks and expect standards to tighten further in Q3. Firms feel it too: more reported higher interest rates on bank loans than in the previous survey. With the ECB now hiking, funding costs are set to keep rising into year-end.
|
|
|
|
Loan Market: Pipeline Reopens
|
|
European leveraged loan issuance reached €214.8bn in H1 2026, up 6% year-on-year. But net supply stayed negative and a technical squeeze drove European loan spreads to nine-year tights in June. September brought relief, with the pipeline above €20bn by mid-month and new deals from AkzoNobel and Suse fuelling expectations of record volume. Some borrowers switched from floating-rate loans to fixed-rate high yield bonds to hedge against further rate hikes.
|
|
|
|
CLO Market: Record Pace
|
|
The market posted €58.22bn in H1 2026, the strongest first half on record. Activity continued in Q3: European volume rose to €10.7bn in September, with new issuance back in the lead, taking year-to-date issuance to €94.9bn across 229 deals. AAA spreads tightened, and European middle-market CLO volume passed €1bn for the first time. Rising base rates help: KBRA expects strong demand for CLO liabilities, supported by recent and potential further rate hikes.
|
|
|
|
|
|
|
BK Opp. Fund 7: Performances
|
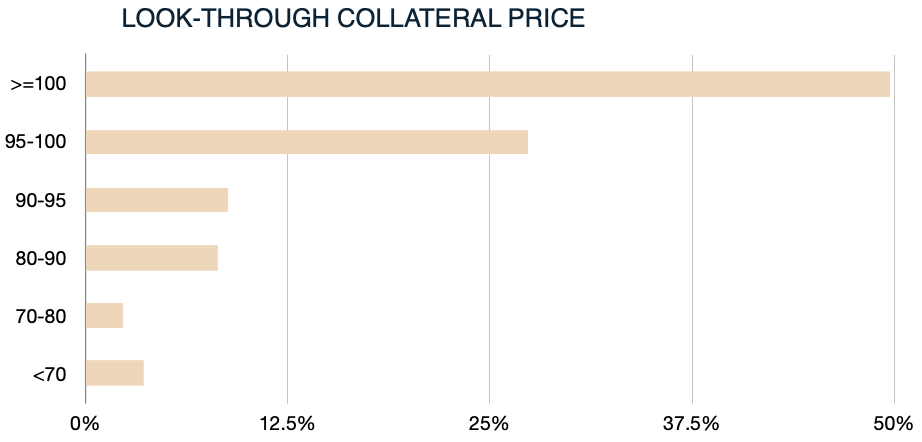
BK Opportunities Fund 7 (BK-7) was launched in Q2 2021. Over the years, we have actively traded BB and B-rated tranches of European CLOs. Our portfolio has remained very diversified across all sectors, with a very low idiosyncratic exposure. In addition to capturing the usual extra return of CLOs from its niche market, we have employed various structural arbitrage strategies, in some cases linked to the duration of our positions.
|
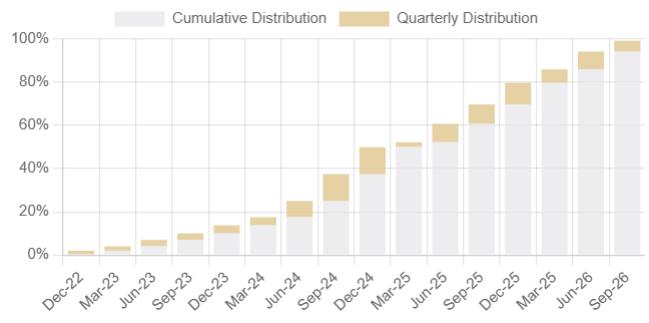
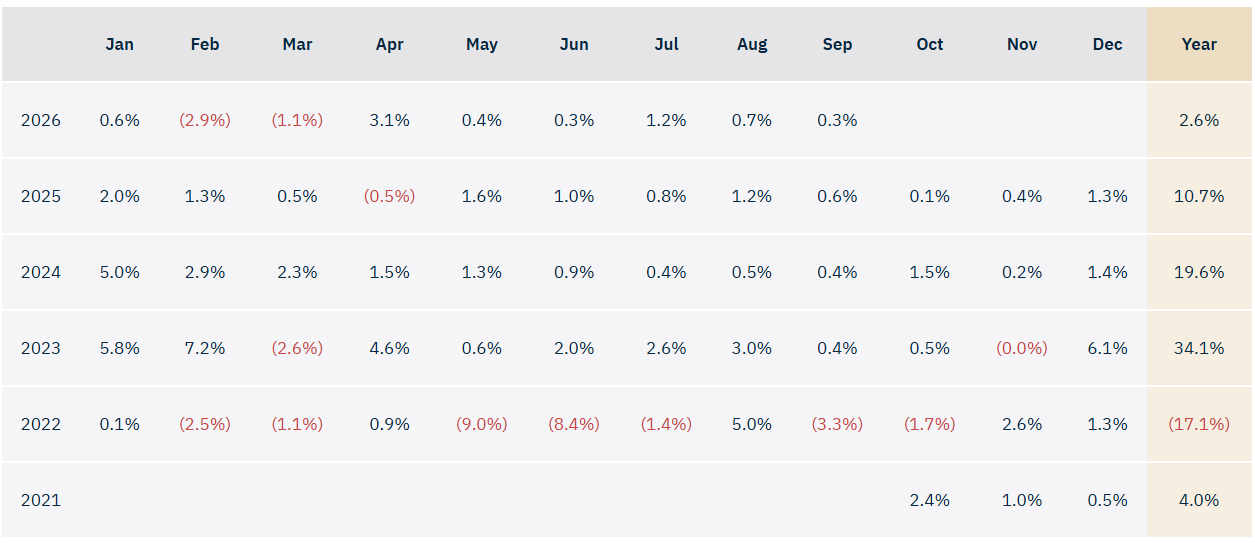
This quarter, BK Opportunities Fund-7 is making a weighted average distribution of 5.0% (non-annualised, based on number of shares). Payments will be wired on 30 Ocotber 2026. The cumulative distribution of the fund is 103.86% (non-annualized, based on the weighted average distribution of all classes), and the annual return since inception is +13.0% (net), materially exceeding our expectations at the fund’s launch.
|
|
The fund has exited its reinvestment phase and is now amortising, so we are focusing on monetising our positions. As we collect coupons & principal and now distribute all proceeds, the fund’s performance should continue to strengthen, and distribution will accelerate.
|
|
|
|
|
|
|
Fund and Market Performances as of 30th September 2026
|
|
|
|
|
Monthly Performances
|
|
|
|
|
Cumulative and Quarterly Distribution
|
|
|
|
|
|
|
Top 10 Industry Exposure
| Industry |
% of Portfolio |
| Healthcare & Pharmaceuticals |
13.6% |
| Services: Business |
9.7% |
| High-Tech Industries |
8.5% |
| Banking, Finance, Insurance & Real Estate |
6.2% |
| Chemicals, Plastics & Rubber |
6.2% |
| Construction & Building |
5.6% |
| Services: Consumer |
4.9% |
| Beverage, Food & Tobacco |
4.8% |
| Capital Equipment |
4.6% |
| Telecommunications |
4.4% |
|
Top 10 Issuers Exposure
| Issuer |
% of Portfolio |
| Liberty Global |
2.1% |
| Ineos Ltd |
1.6% |
| Vmed O2 UK |
1.1% |
| 3I Group |
1.0% |
| Ion Platform |
0.9% |
| Quimper Ab |
0.8% |
| Kantar Global |
0.8% |
|
|
0.8% |
| Claudius |
0.7% |
| Flamigo Lux |
0.7% |
|
|
|
|
|
|
Fund’s Summary
|
| Currency |
EUR |
| Fund’s Inception |
October 2021 |
| Distribution |
Quarterly |
| Investment Manager |
Oristan Ireland DAC |
| Administrator |
Apex Funds Services |
| Custodian |
CIBC Bank & Trust |
| Counsel |
Dillon Eustace |
| Auditor |
Deloitte |
| Bloomberg Page |
BKOPP7A KY <Eqty> |
|
|
Portfolio Manager
Olivier Gozlan
|
|
|
|
|
|
|
|
|
|
This is not for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to law or regulation. The information contained herein is for information only and does not constitute an offer regarding any product. The document has been prepared by Oristan Ireland DAC and the data have not been audited nor verified. Past performance cannot indicate future performance. There is no assurance that the investment objective will be achieved and investment results may vary.
|
|
|
|
|
|
|
|
|